
Categories
BUYING, SELLING, INVESTINGPublished September 18, 2026
What Happens If the Home Inspection Finds Something Major? Ohio Buyer Options Explained
What Happens If the Home Inspection Finds Something Major? Ohio Buyer Options Explained

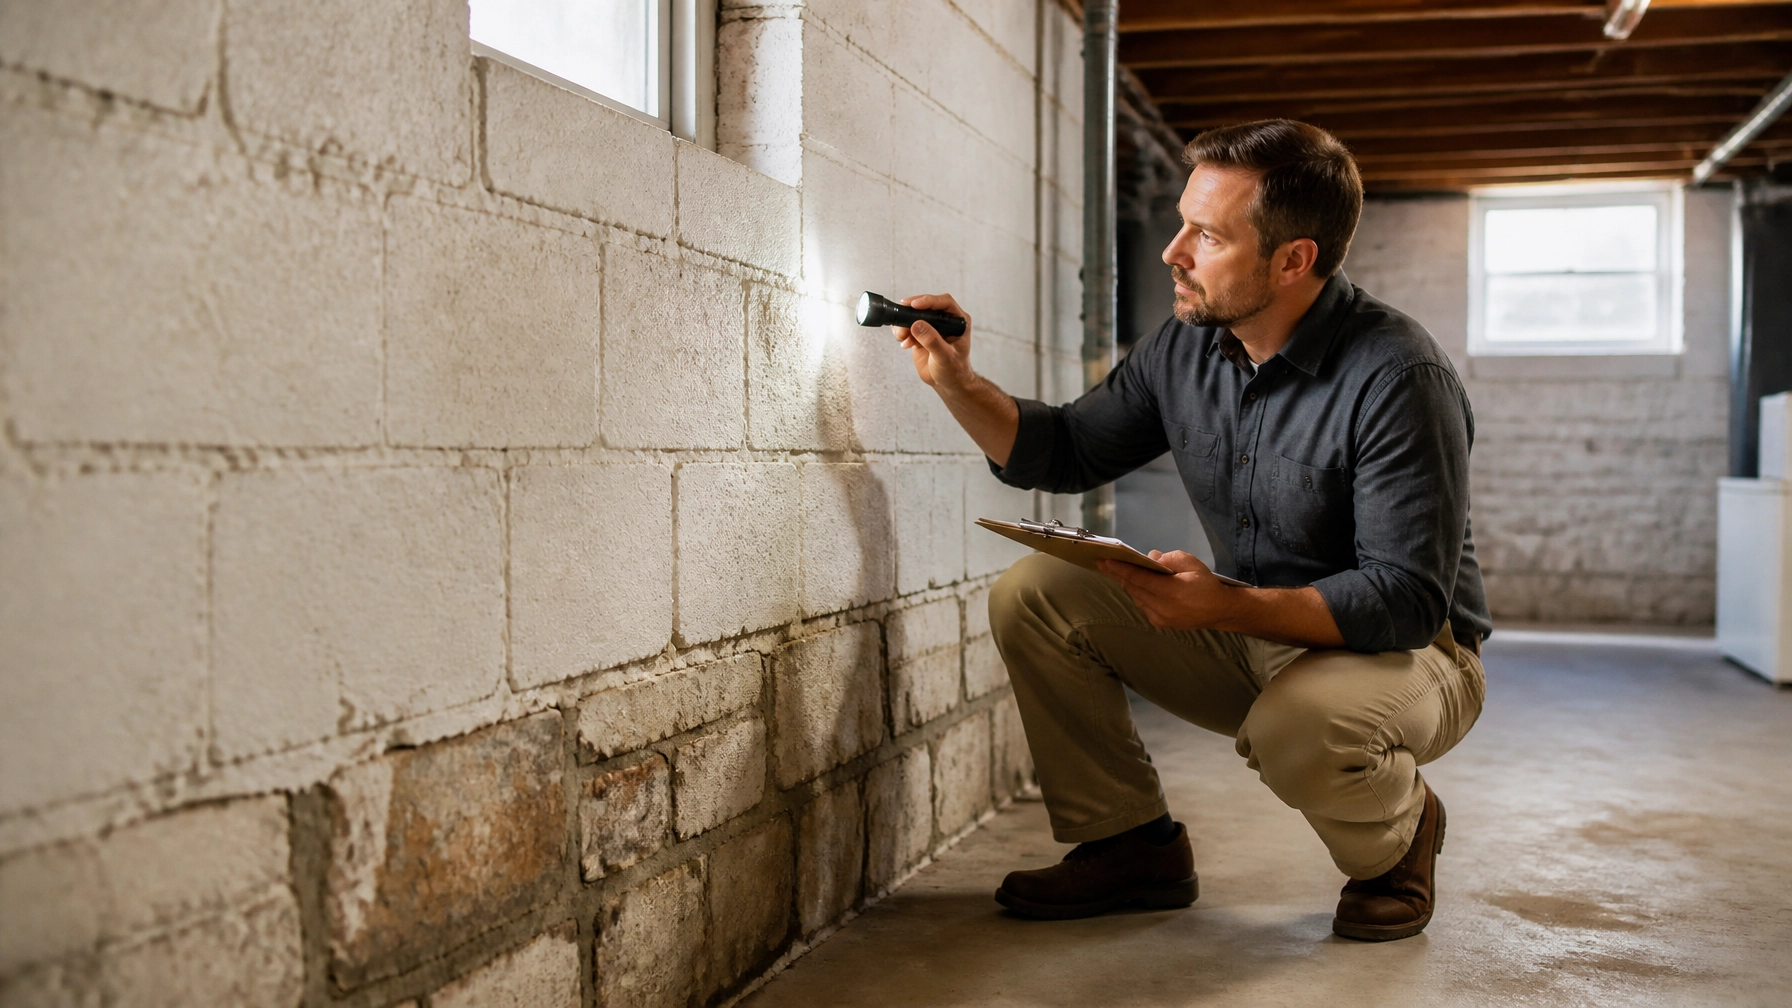
You expected the home inspection to uncover a few loose railings, aging appliances, or a dripping faucet. Those are common. But then the report mentions structural movement, roof failure, unsafe wiring, sewer damage, or water entering the basement…
What happens next?
The first thing to know is that a serious inspection finding does not automatically mean you must walk away. It also does not mean you should ignore the problem because you love the kitchen or already paid for the appraisal.
Your inspection report gives you information. Your purchase contract determines your rights. Your buyer’s agent, lender, inspector, insurance provider, and qualified contractors can help you decide how to use that information before your deadlines expire.
This guide explains your Ohio buyer options and the steps to take when an inspection reveals a major concern.
Important: Contract language and deadlines vary. This article is for general education, not legal advice. Review your specific contract with your buyer’s agent and an Ohio real estate attorney when appropriate.
A Major Inspection Problem Is More Than a Cosmetic Defect
Home inspectors commonly identify maintenance items and minor defects. A cracked switch plate, worn carpet, dated bathroom, or loose cabinet hinge may be worth noting, but these issues usually do not carry the same urgency as a safety, structural, or water-related problem.
A significant concern may involve:
- Structural movement, foundation failure, or serious framing damage
- Roof failure, active leaks, or roof systems near the end of their useful life
- Unsafe electrical wiring, an overloaded panel, or exposed conductors
- Sewer line damage, collapse, or severe blockage
- Ongoing water intrusion, drainage problems, or basement flooding
- Failed or unsafe heating, cooling, or plumbing systems
- Elevated radon levels
- Mold-like growth or conditions contributing to persistent moisture
- Major termite or wood-destroying insect damage
- Conditions that could affect financing, insurance, habitability, or resale value
The word “major” is not a universal legal category. An inspector may describe a condition as a defect, safety concern, recommended repair, or further evaluation. The inspector generally does not decide whether you should buy the house.
That decision depends on the facts, the likely cost, the risk, your financing, the seller’s willingness to negotiate, and the language of your contract.
Older Northeast Ohio Homes Require More Investigation
Many homes in Northeast Ohio have character: and age. A Lakewood bungalow, a Rocky River colonial, or an older property in surrounding Cuyahoga, Summit, Medina, or Lorain County may have systems that have been repaired, updated, or partially replaced over decades.
That history can create complicated inspection findings, including:
- Older roofs installed over multiple layers of shingles
- Masonry foundation cracks or bowing walls
- Aging cast-iron or clay sewer lines
- Knob-and-tube or aluminum wiring in some older homes
- Basement dampness caused by grading, gutters, or drainage
- Older furnaces, boilers, or electrical service
- Unfinished improvements completed without clear documentation
An inspection report may identify a concern without being able to determine the full scope or final cost. That is why a recommendation for a structural engineer, licensed electrician, roofer, sewer contractor, or HVAC professional should not be treated as a routine suggestion.
Sometimes the specialist confirms that the issue is manageable. Sometimes the additional evaluation reveals a much larger problem. Either way, you are making a decision with better information.

Your Ohio Buyer Options After a Serious Finding
Your options depend on your contract, but buyers commonly consider the following paths.
1. Accept the Property As-Is
You may decide to proceed without requesting anything from the seller. This can make sense when:
- The issue is understood and financially manageable
- You have sufficient reserves after closing
- The home’s price reflects the condition
- You are comfortable selecting and managing the repairs yourself
Before accepting the property as-is, confirm that your lender will approve the loan and that an insurance company will provide coverage. A repair that you are willing to live with may still create a lending or insurance problem.
2. Request Repairs
You may ask the seller to correct specific problems before closing. Be precise. Instead of asking for “electrical repairs,” a written request might identify the unsafe condition and request correction by a qualified, licensed professional, along with documentation of the completed work.
Repairs should be clearly documented in writing. Your agent can help communicate the request, but the seller can agree, counter, or decline.
You should also decide whether you are comfortable with the seller choosing the contractor. For complex work, you may prefer a credit so you can select the professional and oversee the result after closing.
3. Request a Seller Credit
A seller credit may help cover eligible closing costs, prepaid expenses, or other permitted transaction costs. It is not always the same as receiving money back for repairs.
Credits are subject to your loan program, lender approval, contract terms, and available closing costs. Your lender should review the proposed credit before you rely on it. A credit that exceeds what your loan and closing structure allow may not provide the benefit you expect.
4. Negotiate a Price Reduction
A lower purchase price may make the repair financially acceptable, especially when you have the cash or financing to complete the work. However, a price reduction may not solve an immediate safety problem, and it may not help if the lender or insurer requires the repair before closing.
Get written estimates before negotiating whenever possible. A $2,000 allowance based on a quick opinion is very different from a $15,000 repair backed by a contractor’s scope of work.
5. Obtain Specialist Evaluations
A general inspector may identify a concern but not diagnose it. For example:
- A foundation crack may require a structural engineer
- A roof concern may require a licensed roofer
- A sewer issue may require a camera scope and written estimate
- An electrical concern may require a licensed electrician
- An HVAC issue may require a service technician
- Elevated radon may require mitigation guidance and follow-up testing
Do not skip specialist evaluations simply because the seller provides an old invoice or says the issue was repaired years ago. Ask what was repaired, when it was repaired, who completed the work, and whether the underlying cause was addressed.
6. Request More Time: If Your Contract Allows It
Sometimes the inspection deadline arrives before you can obtain a structural report or repair estimate. You may ask for an extension, but the seller must agree in writing. Do not assume that a phone call or email automatically extends your rights.
Your buyer’s agent should track the deadline and identify what must be delivered before the contingency period expires. If you need more time, raise the issue early: not on the last afternoon.
7. Terminate Under the Inspection Contingency
Many Ohio purchase contracts allow a buyer who is not satisfied with the property’s condition to request that the seller remedy unsatisfactory conditions. If the parties do not reach an agreement before the contingency period expires, the contract may give the buyer the right to terminate by written notice.
That right is controlled by the exact contract language and required notice procedure. Missing a deadline, using the wrong form, or assuming the contingency automatically continues can create serious consequences.
If you are considering termination, contact your buyer’s agent immediately and consult an attorney if there is uncertainty about your rights or earnest money.

How FHA, VA, Insurance, and the Lender Fit Into the Decision
A home inspection is separate from an appraisal. The appraisal primarily addresses value and, depending on the loan type and property condition, may identify visible concerns that affect the loan.
For FHA financing, the property generally must meet HUD requirements for safety, soundness, and security. Visible roof, electrical, structural, or safety problems may require correction before closing. FHA does not replace your private inspection, and it does not generally test for radon.
VA financing also has property condition requirements. Your lender may identify additional documentation or repair requirements depending on the issue and the appraisal. Ask your lender before agreeing to a repair or credit.
Insurance is equally important. An aging roof, unsafe electrical system, foundation movement, or unresolved water intrusion may affect whether coverage is available or whether repairs are required before the policy can be bound.
A property can pass an appraisal and still have expensive defects. It can also receive a strong inspection report and still face a lender or insurance issue based on separate requirements. Keep all parties informed.
Radon, Sewer, Roof, and Structural Findings Need Special Attention
Northeast Ohio buyers often add radon testing to the inspection process. Radon is invisible and odorless, and a general inspection does not necessarily include testing. The U.S. Environmental Protection Agency recommends taking action at or above 4.0 pCi/L. If results are elevated, buyers may negotiate for mitigation, a credit, or another solution permitted by the contract.
A sewer scope can be especially valuable in older neighborhoods. A collapsed or damaged main sewer line can become a significant expense, even when the plumbing inside the home appears to work normally.
Roof and structural concerns deserve careful evaluation because they can affect safety, financing, insurance, and future resale. Do not rely on a general estimate when the repair could involve foundation stabilization, roof replacement, or major water management.
For additional background, review Milestone Property Group’s Northeast Ohio radon testing guide.
Follow This Step-by-Step Response Plan
When the report identifies something major:
- Read the full report, not just the summary.
- Separate cosmetic items from safety, structural, water, and system concerns.
- Review your inspection contingency and deadlines with your buyer’s agent.
- Schedule specialist evaluations for issues the inspector could not fully diagnose.
- Get written repair estimates and scopes of work.
- Contact your lender and insurance provider about requirements.
- Choose your preferred solution: accept, repair, credit, price reduction, extension, or termination.
- Put all agreements in writing before the deadline.
- Verify completed repairs with invoices, permits, warranties, and reinspection when appropriate.
- Make the decision based on risk: not pressure.
Your agent’s role is not to tell you that every house is perfect or that every defect is a reason to leave. It is to help you understand the market, organize the information, negotiate strategically, and keep the transaction moving while protecting your interests.
Milestone Property Group helps Northeast Ohio buyers navigate inspections, appraisals, financing, and closing with a clear plan. Visit our home buying resources, review financing options, or connect with the team before an inspection issue becomes a last-minute emergency.
The inspection found a problem. That does not automatically end the deal: but it does mean you need to understand the problem, protect your deadlines, and choose your next step deliberately.
Carly Sablotny
REALTOR | Milestone Property Group | Keller Williams Living | PLACE
or another way